Paycheck calculator 2026: what you actually take home
Enter a salary or hourly rate and your state for federal tax, FICA, state tax and your net pay per paycheck, on 2026 IRS rates.
A federal income tax calculator, a state income tax calculator and an after tax salary calculator, in one.
Tap a state to run it, on $65,000 a year
Take-home pay per paycheck (26/yr)
$2,092.60
$54,408 a year from $65,000 gross, in Texas.
Take-home pay $2,092.60 per paycheck (26/yr), $54,408 a year, in Texas.
- Take-home pay 84%
- Federal income tax 9%
- Social Security (6.2%) 6%
- Medicare (1.45%) 1%
Which federal brackets your income fills
2026, singleOnly the part of your income inside each band is taxed at that band's rate. Your taxable income of $48,900 fills the bands below; the darker one is where your last dollar lands, which is your 12% marginal rate.
Breakdown
Texas, 2026| Item | Per paycheck | Per Year | % of gross |
|---|---|---|---|
| Gross pay | $2,500.00 | $65,000 | 100.0% |
| − Federal income tax8.6% | $216.15 | $5,620 | 8.6% |
| − Social Security (6.2%)6.2% | $155.00 | $4,030 | 6.2% |
| − Medicare (1.45%)1.5% | $36.25 | $943 | 1.5% |
| − Texas income tax0.0% | $0.00 | $0 | 0.0% |
| Take-home pay | $2,092.60 | $54,408 | 83.7% |
Your tax rates
- Effective rate 16.3%
- The share of your whole $65,000 that goes to tax. This is the one to quote when comparing offers.
- Marginal rate 12% federal
- What the next dollar you earn is taxed at. Always higher than the effective rate, and it is why a raise never leaves you worse off.
Estimate of annual tax liability spread evenly across pay periods, using 2026 federal rates, the standard deduction and no Texas income tax. Actual withholding depends on your W-4 and is squared up on your return.
Take-home pay at common salaries (2026, single filer)
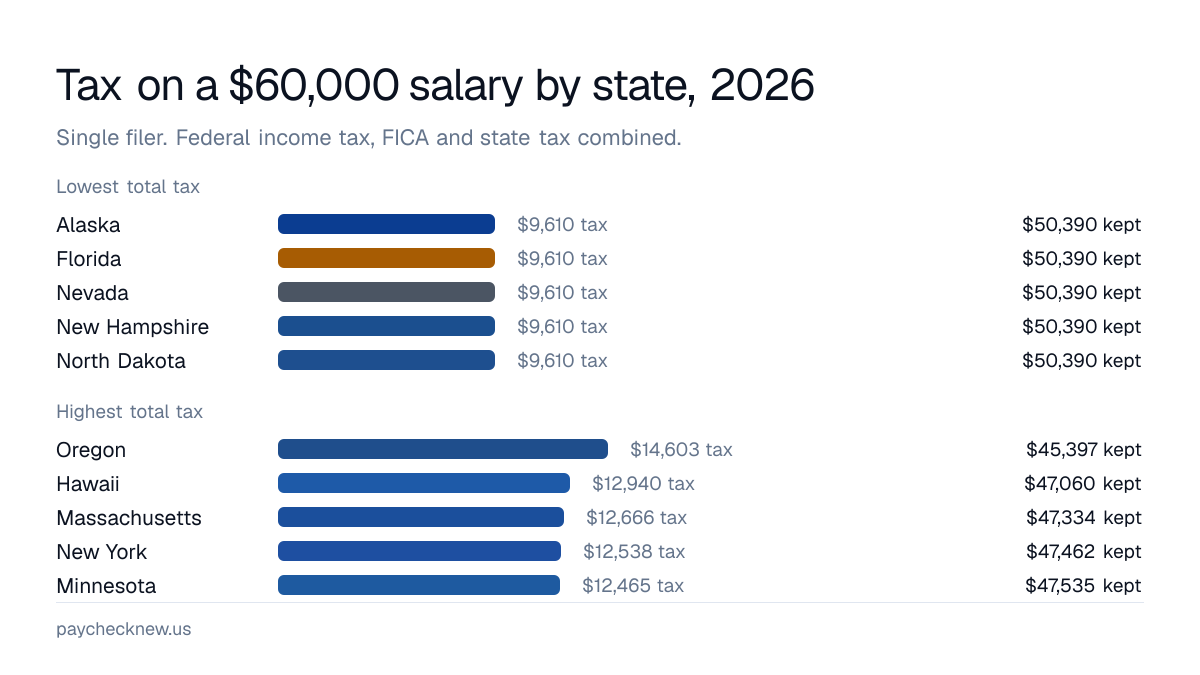
Annual net pay after federal tax, FICA and state tax. No-tax states like Texas and Florida sit at the top; California and New York show the effect of state tax.
| Gross | Texas / Florida | California | New York |
|---|---|---|---|
| $40,000 | $34,320 (14.2%) | $33,104 (17.2%) | $32,570 (18.6%) |
| $60,000 | $50,390 (16.0%) | $47,877 (20.2%) | $47,462 (20.9%) |
| $80,000 | $65,110 (18.6%) | $60,802 (24.0%) | $61,005 (23.7%) |
| $100,000 | $79,180 (20.8%) | $72,772 (27.2%) | $73,874 (26.1%) |
| $150,000 | $113,791 (24.1%) | $102,133 (31.9%) | $105,485 (29.7%) |
What comes out of every paycheck
Federal income tax is progressive: in 2026 a single filer pays 10% on the first $12,400 of taxable income, 12% up to $50,400, 22% up to $105,700, and so on to 37%. Taxable income is your wages minus the standard deduction of $16,100 (single) or $32,200 (married filing jointly). See the full 2026 tax brackets.
FICA is two flat taxes: 6.2% Social Security on wages up to $184,500 and 1.45% Medicare on everything, plus an extra 0.9% Medicare above $200,000. Your employer matches both. Read more on the FICA page.
State income tax ranges from nothing (nine states) to a flat rate (Illinois 4.95%, Pennsylvania 3.07%, Arizona 2.5%) to steep progressive schedules (California up to 13.3%). Pick your state above or open its page below for the full schedule. For the order all six deductions are applied in, and what each one is worth on a real salary, see everything that comes out of a paycheck.
How to use this calculator
- Step 1
Pick salary or hourly
Salary takes an annual figure. Hourly takes a rate and your usual hours a week, and multiplies by 52, so 40 hours gives the standard 2,080-hour year. Where 2,080 comes from.
- Step 2
Choose your state
All 50 states and DC are in the list. Nine charge no income tax on wages; the rest range from a flat rate to a schedule of brackets, and a few add payroll programmes such as California SDI on top.
- Step 3
Set filing status and pay frequency
Married filing jointly roughly doubles the bracket widths and the standard deduction, so a single-earner couple pays materially less than a single filer on the same salary. The frequency you choose is the one the headline figure is shown in.
- Step 4
Open deductions if they apply
A traditional 401(k) reduces income tax but not Social Security or Medicare. Health premiums under a section 125 plan reduce both. Local income tax applies in a minority of states, most visibly Maryland, Ohio and Pennsylvania.
Every figure is an estimate of annual liability spread evenly across pay periods, not a copy of your employer's withholding. How the numbers are produced and tested.
Why use this one
- Nothing is sent anywhere
- The calculation runs in your browser. Your salary, state and deductions are never transmitted, logged or stored, and closing the tab discards them.
- Current 2026 figures
- Federal brackets, the standard deduction and the Social Security wage base come from the IRS release for 2026, and every state page cites that state's own revenue department. See the methodology.
- All 51 jurisdictions
- Every state plus DC, including the ones most calculators skip: state payroll programmes such as California SDI and Washington's WA Cares, local income tax, and reciprocity between states.
- No signup, no upsell
- There is no account, no email capture and nothing to buy. The tool is the whole product, and it prints or saves to PDF from the button in the form.
What people use it for
Comparing a job offer in another state
The same gross can differ by thousands a year once state tax is counted. Run both states and compare net, then read which state taxes you if you would live in one and work in the other.
Deciding a 401(k) contribution rate
Raise the percentage and watch take-home against the amount going into the plan. The gap between them is the tax you would otherwise have paid, which is the real cost of contributing.
Sanity-checking a pay stub
Enter your gross for the period and match the frequency. A difference usually traces to a pre-tax benefit, a local tax, or year-to-date Social Security having passed the wage base.
Turning an hourly rate into a salary, or back
The hourly to salary and salary to hourly pages do the conversion at every common rate, with the after-tax figure alongside.
Planning as a freelancer
A 1099 contractor pays both halves of FICA, 15.3%, in quarterly instalments. This tool models W-2 employment, so treat its FICA line as roughly half of what you will owe. Self-employment tax.
Frequently asked questions
How is take-home pay calculated?
Start with gross pay, subtract pre-tax deductions such as a traditional 401(k) and health premiums, then subtract federal income tax (2026 brackets after the $16,100 single / $32,200 married standard deduction), Social Security (6.2% up to $184,500), Medicare (1.45%, plus 0.9% above $200,000) and any state and local income tax. What is left is your net pay.
Why is my actual paycheck different from this estimate?
This calculator spreads your annual tax liability evenly across pay periods. Your employer withholds using IRS Publication 15-T and the details on your W-4, so each check can be higher or lower. The difference shows up as a refund or balance due when you file. Bonuses, overtime, and mid-year raises also push individual checks away from the average.
Which states have no income tax?
Nine states levy no tax on wages: Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Washington and Wyoming. Washington employees still pay Paid Family & Medical Leave and WA Cares premiums, which this calculator includes.
How much is taken out of a $60,000 paycheck?
For a single filer in a no-income-tax state in 2026, roughly $9,610 a year: $5,020 federal income tax, $3,720 Social Security and $870 Medicare, leaving $50,390 or about $1,938 every two weeks. In California the same salary nets about $47,877.
Does the calculator include local or city taxes?
Only if you enter a rate. City and county income taxes apply in parts of Pennsylvania, Ohio, Maryland, Indiana, Kentucky, Michigan, Missouri, New York City and a few others. Each state page tells you whether you are likely to owe one, and Maryland defaults to a typical county rate because every county levies it.
Is a 401(k) contribution taken out before tax?
A traditional 401(k) or 403(b) contribution reduces your federal and (in most states) state taxable income, but not Social Security or Medicare wages. Section 125 health premiums reduce all of them. Roth contributions reduce none, so leave the 401(k) field at zero if yours is Roth.
Paycheck calculator by state
What this loads into your browser, against the alternatives
Every paycheck calculator says it is accurate and none shows you why to believe it. Here is one thing you can check yourself in a browser tab, measured on 8 September 2026: the cookies each one sets and the outside domains it contacts before you have typed anything.
- PaycheckNew0 cookies, 1, cookieless hosts
- PaycheckCity121 cookies, 165 hosts
- SmartAsset51 cookies, 61 hosts
- Gusto27 cookies, 9 hosts
- ADP25 cookies, 36 hosts
Nothing you type here reaches a server, because there is no server to reach. The full comparison gives the method so you can repeat it, and is honest about the four things the bigger tools do better than this one.
Other related calculators
- Payroll tax calculatorWhat an employee costs an employer, and what comes out of their pay. Both sides, one page.
- Bonus tax calculatorWhat lands in your account after the flat 22% withholding, and what comes back.
- Commercial loan calculatorMonthly payment, total interest and the year-by-year balance on a business loan.
Hadi · Developer and maintainer
Federal tables checked against the IRS 2026 inflation adjustments on . State figures, where quoted, are each state's latest published schedule, 2025; federal figures are 2026.